
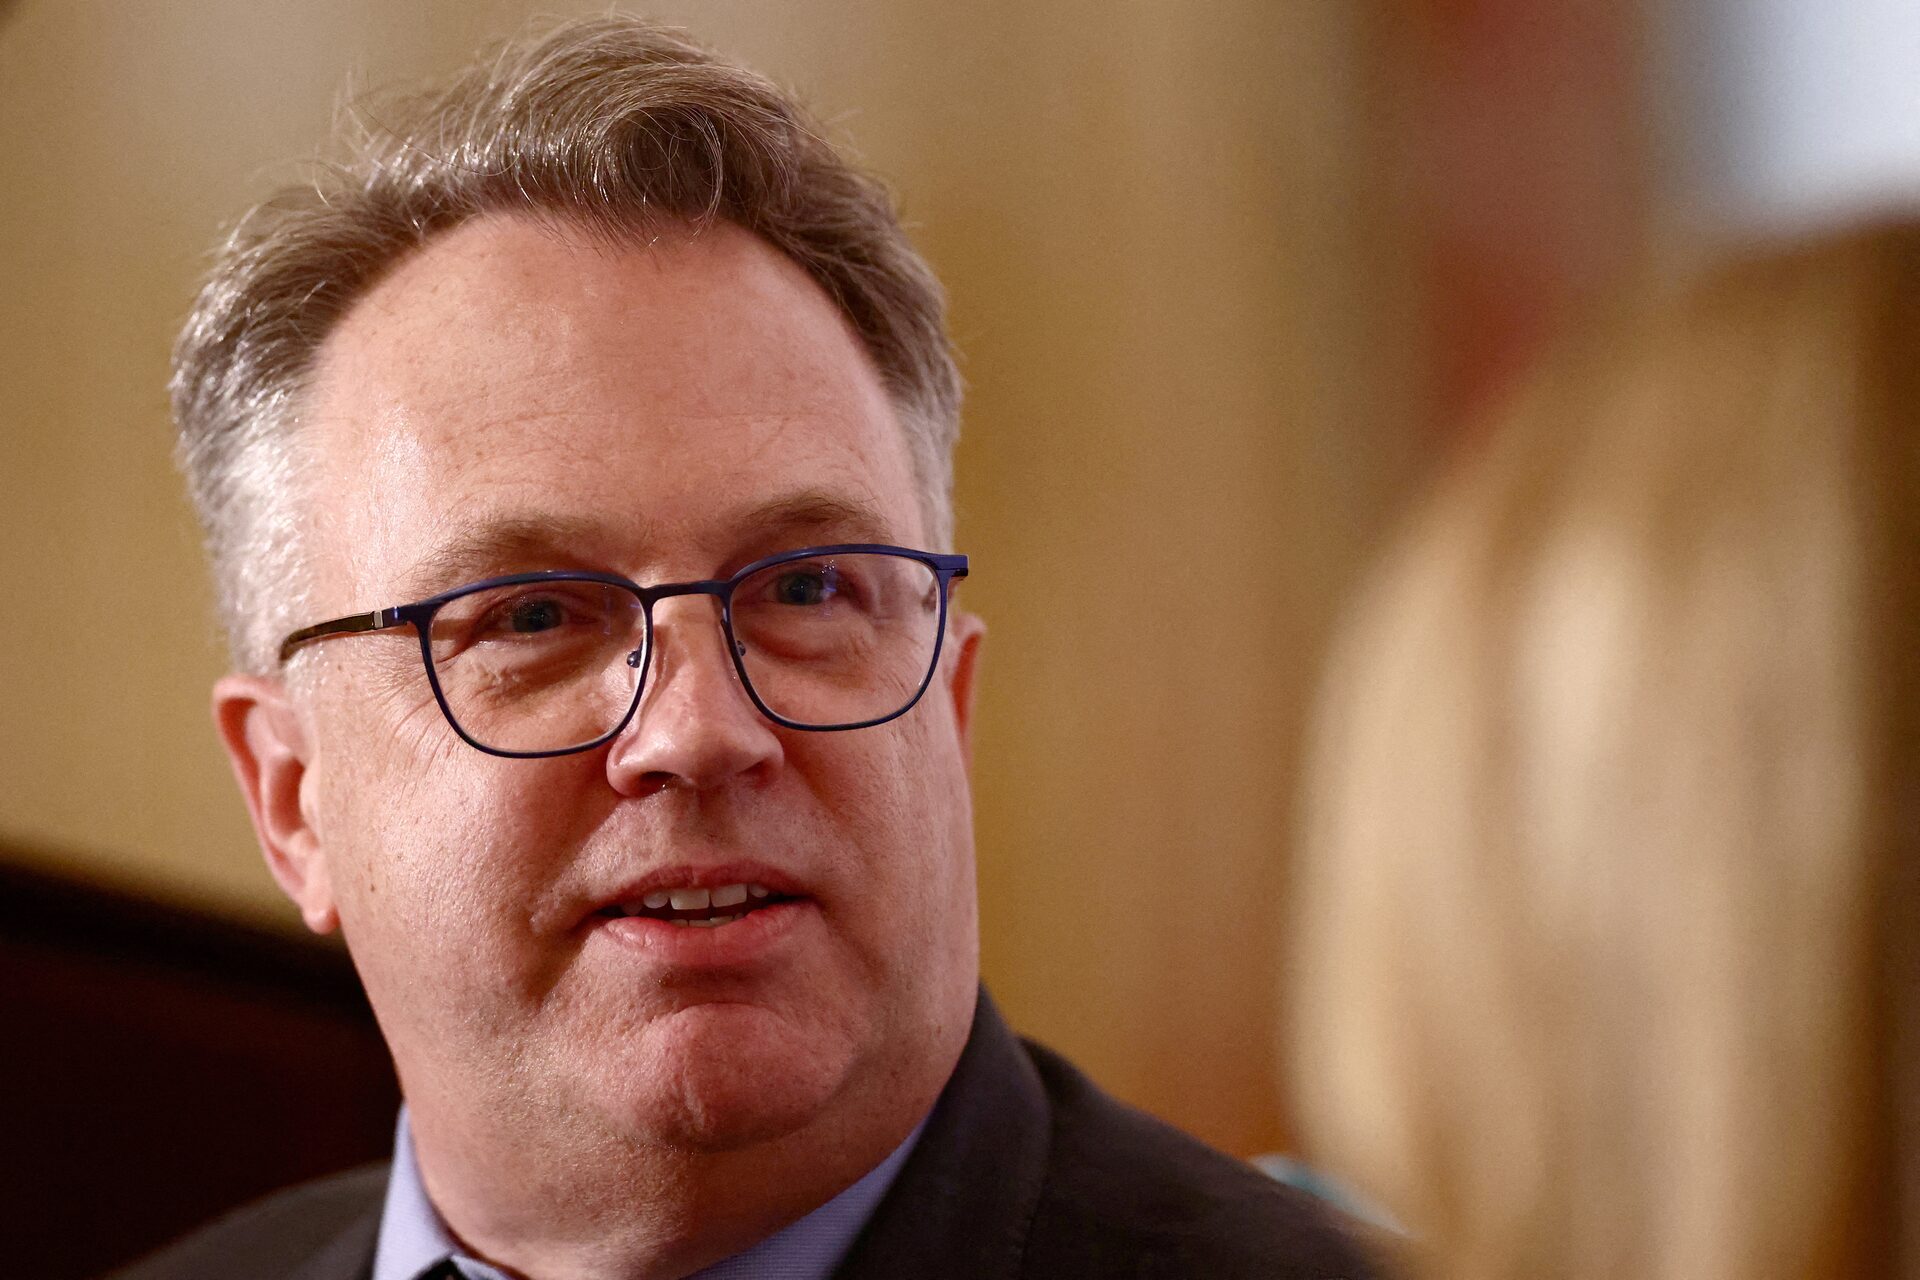
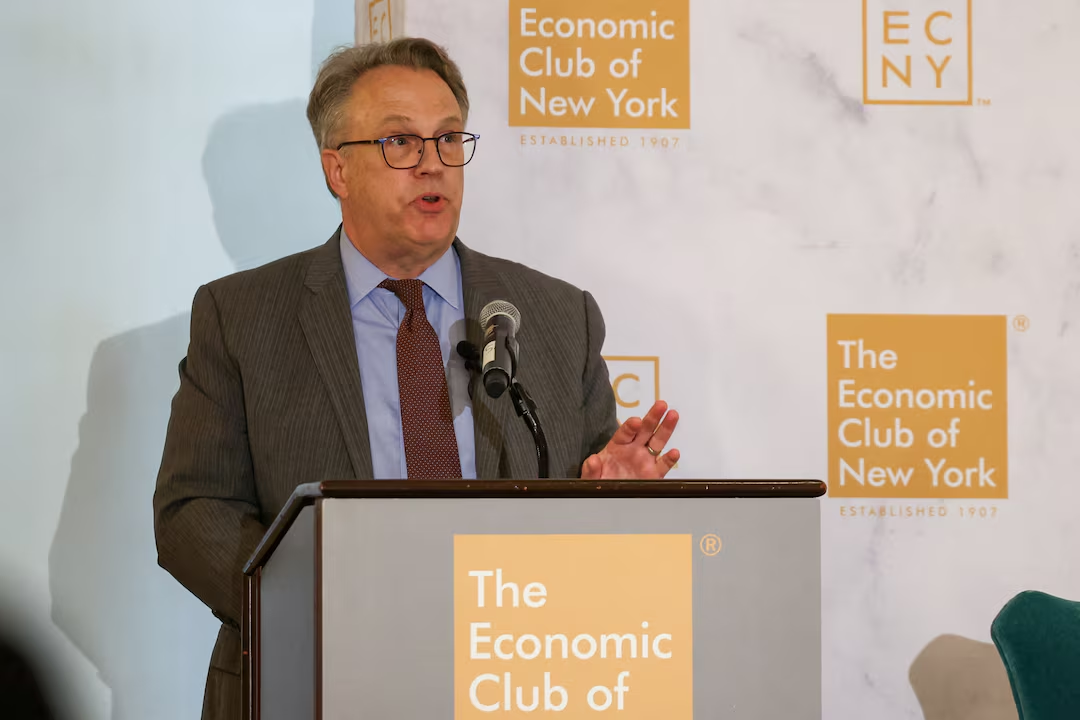
New York Federal Reserve President John Williams said on Friday that the central bank's current interest rate policy is appropriate given the economic outlook, even as inflation remains stubbornly elevated. Speaking in a public appearance reported by Michael S. Derby, Williams noted that the personal consumption expenditures (PCE) price index is running around 4%, with core inflation above 3%. The federal funds rate target range currently sits at 3.5% to 3.75%, a level Williams argued is sufficient to restrain demand without choking growth. His remarks come as financial markets are pricing the Fed on hold but are increasingly weighing the possibility of a rate hike if inflation does not moderate. Williams expects inflation to ease in the coming months as tariff impacts fade and the recent energy shock subsides, but he offered no timeline for rate cuts. The statement reinforces the Fed's patient stance at a moment when sticky inflation is testing the central bank's credibility. Why this matters now: with PCE inflation running a full percentage point above the funds rate in real terms, the Fed is effectively running negative real rates. That policy stance historically has been associated with accelerating inflation, not disinflation.
Where the 3.5%–3.75% Rate Floor Came From
The current federal funds rate target range of 3.5% to 3.75% represents the terminal level of the Fed's 2024–2025 tightening cycle, which paused after the central bank delivered 525 basis points of cumulative hikes. Williams's assertion that this range is "appropriate" signals that the Federal Open Market Committee sees no immediate need to adjust rates, even as inflation data continues to run hot. The decision to hold reflects a deliberate bet that the current policy stance is restrictive enough to gradually cool the economy without triggering a recession. Williams's own projections, embedded in the Fed's Summary of Economic Projections, show the median FOMC participant expecting the funds rate to end 2026 near current levels. The 3.5%–3.75% range is roughly 150 basis points above the Fed's estimated neutral rate of 2.0%–2.5%, which gives the committee some cushion. However, with PCE inflation at 4%, the real federal funds rate is negative 0.25% to 0.50%. That level is historically accommodative. Williams's confidence that inflation will ease rests on the assumption that transitory factors, particularly tariffs and energy prices, will reverse. If those assumptions prove wrong, the current rate floor will look too low, and the Fed will face pressure to resume hikes. The FOMC's June meeting will provide the first formal test of whether the committee's patience holds or fractures under incoming data. The Fed's dot-plot projections, due for an update at that meeting, will tell markets whether the median FOMC member still sees the funds rate ending 2026 near current levels or whether the dots have shifted upward toward a hike. A shift of even 25 basis points in the median dot would signal a material change in the committee's confidence and would be read by markets as a hawkish pivot.
How Sticky Inflation Flows Through the P&L
For banks and financial institutions, the persistence of inflation above 3% creates a complex operating environment. On the asset side, higher-for-longer inflation supports net interest margins, as banks can reprice loans upward while deposit costs lag. The current 3.5%–3.75% funds rate gives lenders a comfortable spread over the near-zero deposit rates many still pay. But the negative real rate environment also erodes the real value of fixed-income portfolios, particularly the massive holdings of Treasuries and mortgage-backed securities that banks accumulated during the pandemic. For corporate borrowers, the combination of 4% PCE inflation and 3.5%–3.75% short-term rates means that real borrowing costs are negative for many floating-rate loans. This dynamic encourages leverage and inventory accumulation, which in turn keeps demand elevated and inflation sticky. The Fed's patient stance effectively subsidizes borrowing in real terms, creating a feedback loop that makes disinflation harder to achieve. For equity markets, the message is mixed: rate stability supports valuations, but the absence of rate cuts means the cost of capital remains elevated for growth companies. The market's growing expectation of a rate hike introduces uncertainty that depresses risk appetite and increases the premium investors demand for holding long-duration assets. Bond markets are pricing this tension directly: the two-year Treasury yield has climbed above the ten-year in recent sessions, reflecting investor conviction that the Fed will hold rates high rather than pivot. Credit spreads on investment-grade corporate bonds have widened modestly, signaling that corporate treasurers are beginning to factor in the possibility that the next Fed move is a hike rather than a cut. Small-cap equities, which carry higher floating-rate debt loads than large caps, are underperforming as a result. The repricing is early but directionally consistent with a scenario in which Williams's confidence in disinflation is not shared by the broader market.
The Competitive Reshuffle Among Banks and Asset Managers
Williams's hold-steady posture creates clear winners and losers across the financial landscape. Large money-center banks with diversified funding bases and floating-rate loan books benefit from the current rate environment, as they can maintain wide net interest margins without the cost pressure of a hiking cycle. JPMorgan Chase and Bank of America have consistently reported net interest income growth in the 3.5%–3.75% rate environment. Regional banks face a more precarious position: their deposit costs are rising as customers seek higher yields, compressing margins even as the Fed holds rates steady. The negative real rate environment also pressures insurance companies and pension funds, which rely on nominal yields to meet long-term liabilities. With PCE inflation at 4%, a 3.75% Treasury yield delivers a negative real return of 25 basis points. Asset managers are shifting allocations accordingly: inflows into Treasury Inflation-Protected Securities have accelerated, and demand for floating-rate debt has increased as investors seek to hedge against the risk of a rate hike. The Fed's patience also benefits private credit funds, which can offer borrowers floating-rate loans at spreads that look attractive relative to negative real Treasury yields. The competitive dynamic favors institutions that can pass through inflation risk to borrowers and penalizes those with fixed-rate liabilities or long-duration asset portfolios.
Downstream Effects on Hyperscalers, Fabs, and Enterprise Buyers
The Fed's decision to hold rates at 3.5%–3.75% while inflation runs at 4% has direct consequences for capital-intensive industries. Hyperscalers such as Amazon Web Services, Microsoft Azure, and Google Cloud are in the middle of a $100B–$700B collective capex cycle for AI infrastructure, much of it financed with floating-rate debt. A negative real rate environment encourages them to accelerate spending, as the real cost of borrowing is negative. This supports demand for semiconductor fabrication plants, data center construction, and networking equipment. For fabs like TSMC and Samsung, the Fed's stance means their customers face lower real financing costs, which sustains order books for advanced nodes. Enterprise buyers of IT infrastructure face a more nuanced calculus: the cost of capital for on-premise data center builds remains elevated in nominal terms, but negative real rates make leasing or colocation arrangements more attractive relative to cash purchases. The energy sector is a direct beneficiary of the Fed's patience: with PCE inflation driven partly by energy shocks, oil and gas producers see higher revenues while their borrowing costs remain fixed. The negative real rate environment also supports commodity prices, as investors rotate out of cash and into real assets. For the housing market, the combination of 4% inflation and 3.75% mortgage rates means that real mortgage rates are negative, which sustains demand even as nominal affordability metrics look stretched.
The Policy Signal Behind Williams's Patience
Williams's statement that current rate policy is "appropriate" is more than a tactical pause. It represents a strategic read on where the Fed believes the economy is heading. By explicitly citing tariff impacts and energy shocks as transitory factors, Williams is signaling that the FOMC views the current inflation overshoot as supply-driven rather than demand-driven. This distinction is critical: if inflation is supply-driven, raising rates would do little to lower prices and would risk unnecessary economic damage. The Fed's patience is therefore a bet that the disinflationary forces of fading tariffs and stabilizing energy markets will prove stronger than the inflationary impulse from negative real rates. The market's growing expectation of a rate hike shows that investors are less confident in that bet. Williams's remarks also serve a communications function: by reiterating the appropriateness of current policy, he is trying to anchor expectations and prevent the market from pricing in rate hikes that could tighten financial conditions prematurely. The Fed is walking a narrow line between maintaining credibility on inflation and avoiding a policy error that would tip the economy into recession. The next two months of inflation data will determine whether Williams's patience is vindicated or whether the Fed must abandon its hold-steady posture and resume tightening.
The critical question for the second half of 2026 is whether the Fed's patience will be rewarded or punished. If tariff impacts fade and energy prices stabilize as Williams expects, PCE inflation may drift back toward 3% by year-end, allowing the Fed to maintain its current rate stance and eventually pivot to cuts in 2027. But if inflation proves stickier, driven by wage growth, housing costs, or a rebound in consumer demand, the negative real rate environment will force the Fed's hand. A rate hike from the current 3.5%–3.75% range would mark a dramatic reversal of the 2024–2025 pause and would likely trigger a sharp repricing of risk assets across equities, credit, and real estate. Williams's confidence rests on the assumption that the current inflation is transitory, an assumption that has proven wrong before. The June FOMC meeting and the May PCE print due in late June represent the next major data checkpoints. Markets will scrutinize both for confirmation that the disinflationary narrative holds. Until then, the Fed's hold-steady posture keeps investors in a state of productive uncertainty, and that uncertainty is itself a form of tightening financial conditions without moving the policy rate.
The BossBlog Daily
One email with the AI markets brief — the 13F moves, the Congressional trades, and what changed. No fixed schedule and no filler: it goes out when there is something worth sending.
Unsubscribe any time. We never sell or share the list.